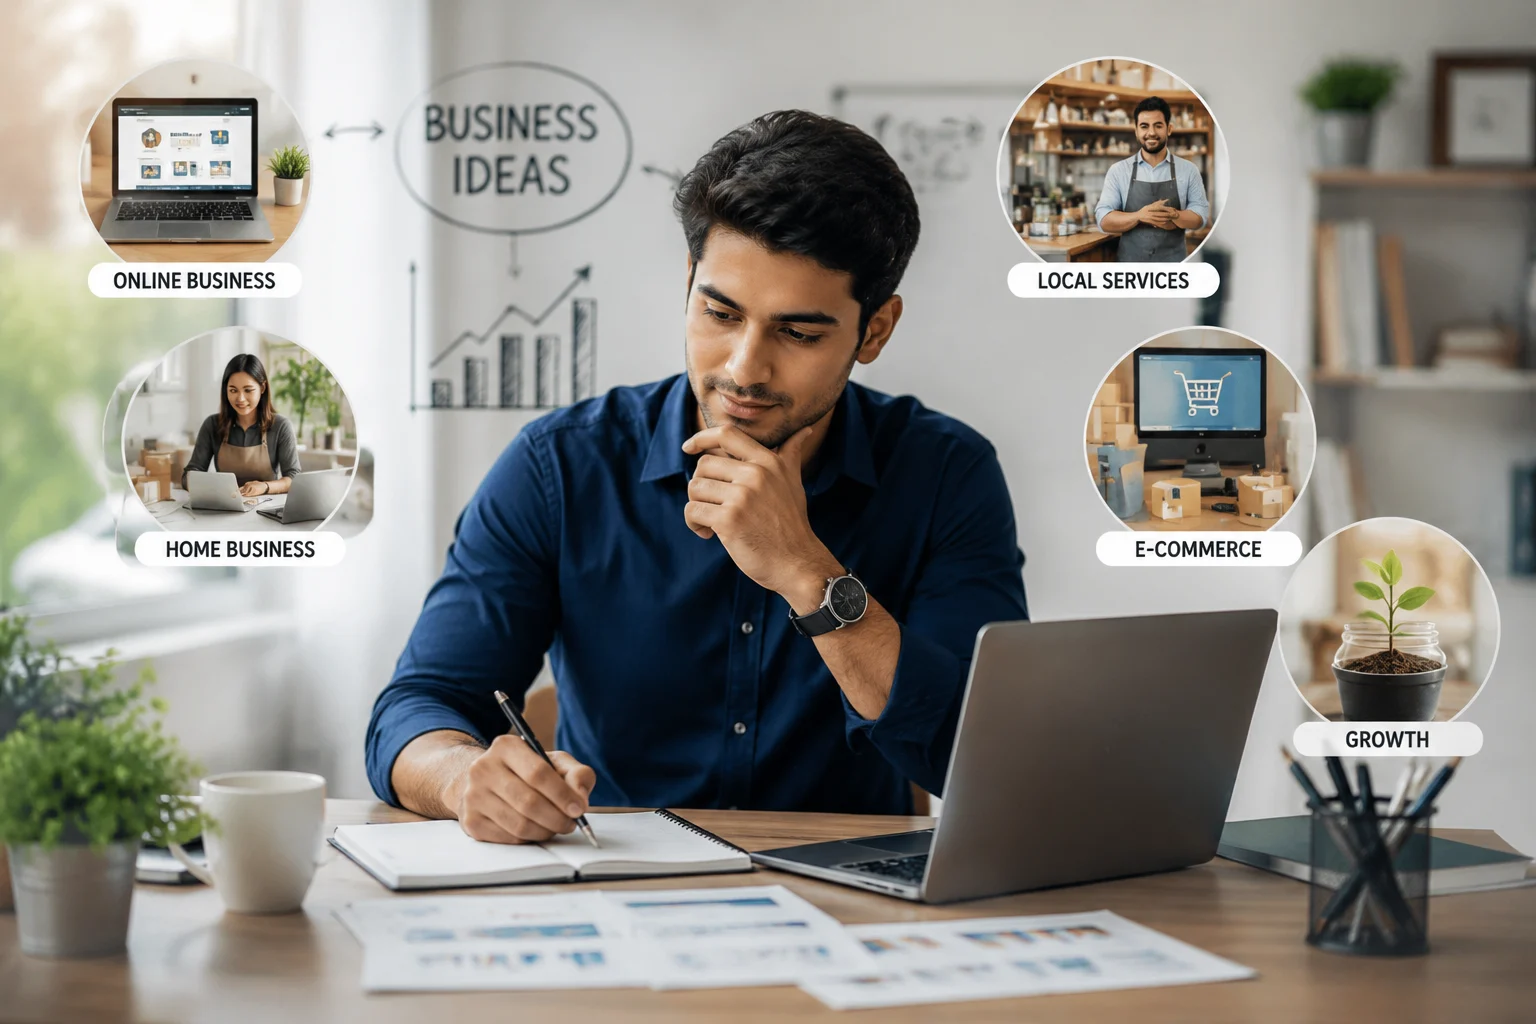
Coming up with a business idea is easy. It is WAY more difficult to find an idea that aligns with your skill set, solves a real problem, has paying customers, fits your budget, and offers a realistic path to profit. When described in a single sentence, thousands of potential businesses can seem tempting. Start a cleaning business, an online store, become a consultant, sell digital products or food — there are many options; you can rent properties, create software applications, offer home services, teach anything, and network all industries that you find specialize enough to serve. But an idea alone doesn’t tell you whether people will pay for it, whether it is economically viable to reach that customer, or what the overall cost of back-end expenses, taxes, and competition would be day in and day out.
Entrepreneurship offers a massive opportunity. There are millions and millions of small businesses in the United States representing the majority of all U.S. business and employing millions of people as defined by the U.S. Small Business Administration’s Office of Advocacy. Census Bureau data also show that millions of firms have no employees, proving entrepreneurship isn’t just at the helm of some massive company. Other entrepreneurs want to form organizations that will hire dozens, maybe hundreds, of people in due time. Meanwhile, some want a lucrative owner-operator, niche practice with minimal competition or an internet business. Others want local service work or flexible work-from-home options.
That is why the most beneficial question is not: “Which one is the best business idea? The real question is, “Which business opportunity offers the best blend of customer pull, my own ability, economically viable unit economics, a tolerable degree of risk, and scalability? This Businesslineer guide helps with that. It covers different types of business ideas, gives you a realistic way to assess opportunities, and walks you from brainstorming to validation and launch.
What Makes a Business Idea Worth Pursuing?
A business idea is a concept. When that concept connects to an actual customer, a strong need, and a feasible economic vehicle to deliver the solution, it becomes a business opportunity. Say a person says, “I want to open a digital marketing agency…” That is a concept, but it still doesn’t allow for any serious assessment. Who will the agency serve? What problem will it solve? How will it give customers a reason to choose it over established rivals or freelancers? How will clients be acquired? What can the agency charge? How long will each account take? What is the background of the founder? Do customers need the service again and again?
Answering those questions turns an abstract notion into a testable hypothesis. While an interesting concept often means a promising business. It identifies customer, problem/solution fit, price/What, and go-to-market plausibly and makes money on the operation.
Start With a Problem, Need, or Desired Outcome
The best businesses help customers make progress. That progress often comes from solving a problem or improving an existing situation. A plumbing company repairs a leaking pipe, a bookkeeping service helps manage finances and paperwork, and a cleaning company saves customers valuable time. Each business provides a solution that makes life easier or helps customers achieve a desired outcome.
Other businesses focus on fulfilling wants rather than solving urgent problems. A wedding photographer helps couples preserve important memories. A specialty food brand creates an enjoyable experience. A design company helps another business build a more professional image.
The problem does not need to be revolutionary. Many successful businesses simply create better, faster, more convenient, or more affordable solutions to problems customers already understand. Before becoming attached to an idea, ask what customers are actually buying.
Someone hiring a lawn-care company is not only paying for grass cutting. They may be buying more free time, a better-looking property, convenience, compliance with neighborhood expectations, or relief from physical work. Understanding the final outcome makes it easier to create a stronger offer and communicate the value customers receive.
Look for Evidence of Demand
Positive feedback from friends and family is not the same as market validation. Real demand is shown through customer behavior. People demonstrate demand when they already spend money on similar solutions, actively search for help, complain about existing options, ask for recommendations, or try to solve the problem themselves.
Market research provides stronger evidence. The U.S. Small Business Administration recommends studying factors such as customer demand, market size, location, competition, pricing, demographics, and existing alternatives. This research helps entrepreneurs understand whether a business idea has a realistic opportunity in the market.
Do not let competition put you off right away. With existing competitors, you can show that potential customers are already paying for something similar to what you’re proposing. More concerning questions are: is there space for another provider, and do you have a compelling reason to turn firms into clients? An unseated market can be an opportunity, or it can be so devoid of competition that the landscape is too thin to support a business beyond MVP. That research helps differentiate between those possibilities.
Make Sure the Economics Can Work
Not all businesses that generate revenue are attractive business ideas. Let’s say you have two businesses that both make $10,000 every month. On one hand, you need $8,500 for inventory, labor, advertising, transportation, software, refunds, and other operating expenses; on the other, you need $3,500. The revenues are the same, but the economics are fundamentally different.
When evaluating a business idea, consider several important factors. Ask whether you can realistically charge the expected price, how often customers may purchase, and how much it costs to deliver the product or service. You should also calculate fixed operating expenses, customer-acquisition costs, and the amount of time you must personally invest as the owner.
Profitability usually comes from the relationship between these factors rather than from simply operating in a so-called “profitable industry.” A business may appear attractive on the surface but still struggle if costs are too high, customers are expensive to acquire, or the owner’s time is not used efficiently.
This is why claims such as “this business generates six figures” should be viewed carefully. Some businesses can produce significant revenue, but revenue alone does not guarantee profitability or personal income. The real measure is how effectively the business converts revenue into sustainable profit.
Consider Founder Fit
A bad business can still exist in a good market. Whether an idea is feasible is determined by what you already know, your reputation, your interests, connections, money in the bank, risk tolerance when it comes to ideas/people/time/date/month/etc., where you live or travel or could go and work in person, or can survive remotely with a good internet connection. Years of experience managing commercial properties may put you at an advantage in how you deliver services related to them. Conversely, someone with expertise in paid advertising may take a better approach to building an adle service boutique. If you have strong skills in a trade, you can start a local service business with little to no learning cost, rather than learning that trade from the ground up.
This does/is not mean you start a business only around what you are currently doing. You can 100% learn new skills, but starting from different positions involves different amounts of time, money, and uncertainty. Ditto for every business opportunity — a good opportunity must be able to make sense in the market, but also in the mind of the person looking to build it.
How to Choose the Right Business Idea for You
Here are the business iterations that help you avoid searching for the perfect theorized business. This filters thousands of opportunities into a few investments that deserve further exploration. One way to approach this is to start with the constraints instead of your giant list of business ideas.
If your available capital is limited, avoid starting with businesses that require a commercial lease, large amounts of inventory, specialized vehicles, or expensive equipment. These models can create significant financial pressure before you have proven customer demand.
Instead, consider opportunities that require fewer upfront resources. Location-independent services, digital products, remote consulting, tutoring, and certain online businesses can often be started with lower overhead. E-commerce can also be a practical option if you want to sell physical products without relying on a traditional storefront.
Your available time is another important factor when choosing a business idea. A business that requires daytime availability can be difficult to manage if you already have a full-time job. In that situation, consider a flexible service, online business, or appointment-based model.
Another option is a project-based online service that allows you to work around your existing schedule. You could also offer services during evenings or weekends by appointment. A business model that fits your available time is more likely to remain sustainable in the long run.
Your long-term goal is also important. Think about how you can delegate, standardize, automate, or otherwise have employees do the work if your goal is to create a bigger company. A business model that requires your hands-on labor for everything might generate fantastic income as a self-employed person but has limited scalability.
Lifestyle also matters more than many business idea lists like to admit. Some business people like to be hands-on with customers; others don’t—others also prefer analytical, creative, technical, or operational work. Some want a homegrown local company, rooted in their community; others value geographic flexibility. It means you need to separate what you can do from what you are actually willing to do, over and over. This is not to say you can put websites together and spend the next five years of your life massaging web-design clients.
Once these details are clear, the broad business-idea categories below give you a solid framework for considering your options.
Small Business Ideas
Small businesses include a wide range of models, from solo operations to established companies with employees, real estate, equipment, and multiple revenue streams. For many first-time entrepreneurs, a small business can be a realistic bridge between employment and business ownership. It allows founders to start with a focused market and expand as customer demand grows.
A local cleaning company is a simple example. The core service may appear straightforward, but entrepreneurs can build many different models around it. These include residential cleaning, commercial office cleaning, short-term rental cleaning, move-in and move-out services, post-renovation cleaning, and specialized cleaning for specific industries or facilities.
The same principle applies to many other small business categories. Landscaping, pet care, mobile auto detailing, bookkeeping, event services, equipment rentals, specialty retail, repair services, and many other industries can be built around specific customer needs. The opportunity becomes stronger when the business solves a clear problem for a defined group of customers.
A successful founder understands exactly who the ideal customer is, what problem that customer needs to solve, and why they would choose one solution over another. For example, “cleaning company” is a broad description, while “recurring office cleaning for independent medical practices” identifies a specific audience and use case. Similarly, “photography business” is general, while “product photography for independent e-commerce brands” creates a clearer market position.
Being specific does not limit growth. In many cases, it improves growth by making marketing, customer acquisition, and service delivery more focused. Once a business establishes itself in a niche, it can expand into related markets, add services, and reach new customer segments.
Small businesses also provide many opportunities for differentiation. Some companies compete through specialization, while others focus on location, convenience, speed, pricing, customer service, quality, technology, or overall experience. The strongest competitive advantage is usually based on something customers genuinely value rather than something the owner simply finds interesting.
Businesslineer already covers individual business models such as cleaning businesses, trailer rentals, vending machines, food trucks, and other entrepreneurial opportunities. These detailed guides are most useful after you identify the type of small business you want to explore. If you are still comparing options, the Small Business Ideas section can help you discover opportunities based on different skills, customer types, budgets, and operating models.
Online Business Ideas
An internet business uses the web to provide a product or service, a market for customers, complete sales transactions, or run the firm itself. That definition includes far more than e-commerce. These businesses can be anything—from high-ticket consulting to freelancing, SaaS (software as a service), online courses, digital content publishing, membership sites & communities, virtual agency work, and more.
Advantage of an online business: It has immense reach. An online company can reach customers all over the country—or even the world — while a local company may find itself relegated to customers within traveling distance. This wider reach can create big opportunities—especially for businesses targeting narrow markets that would be too small in one geographical area.
But online isn’t necessarily easy. Lower barriers to entry can mean more competition. Search, ads, social media, referrals, partnerships, marketplaces, outbound sales, or you already have an audience that takes care of that. Then there’s the risk of platform dependence. If a business relies purely on one source of traffic, be it a marketplace, social network, advertising platform, or search engine, it is subject to changes in policies while not having control over its future.
Online Service Businesses
One of the simplest online businesses to test is services, as it lets you sell expertise without first building convoluted systems. A graphic designer, copywriter, consultant, virtual assistant, web developer, bookkeeper, marketing specialist, recruiter, video-editing filmmaker, translator, or business analyst may only need a clear offer + proof you can deliver that offer + tools to retain clients + a high-quality source of new prospects.
Specialization can strengthen the model. You were the last thing a generic consultant would ever become: instead of telling practices how never to lose another patient, you taught independent dental practices to keep their patients. Rather than video editing in general, you could be editing tutorials for software companies. To offer more than just general bookkeeping, you might do bookkeeping for contractors or accounting for eBay sellers. Clearly understanding your customer environment lets you design better-targeted services for valuable pain points.
E-Commerce and Digital Products
E-commerce businesses have different economics because physical products often involve inventory, manufacturing, fulfillment costs, returns, shipping, and marketplace fees. A product may appear profitable based on its selling price, but expenses can quickly reduce the actual margin. Before scaling, entrepreneurs should understand important factors such as contribution margin, inventory turnover, return rates, fulfillment costs, and cash-flow requirements.
Digital products avoid some of the challenges associated with physical products. However, their low barrier to entry creates another challenge: customers need a strong reason to pay. People can often find free information, templates, tools, and resources online. Successful digital products usually provide clear value through convenience, expertise, organization, productivity improvements, speed, or meaningful time savings.
The Businesslineer Online Business Ideas section can help you compare different models and determine whether selling products, providing services, or operating primarily online fits your goals. You can also explore existing Businesslineer guides on e-commerce, freelancing, writing, design, consulting, and related opportunities for more detailed insights.
Home Business Ideas
A home business can eliminate one of the biggest fixed costs faced by many traditional companies: renting separate commercial space. This makes home-based entrepreneurship attractive for people who want to start gradually, remain flexible, test an idea with less financial risk, or build a business around family and personal commitments.
However, a home business describes where the company operates, not what it sells. A home-based entrepreneur may run a virtual consulting company, tutoring business, design studio, bookkeeping practice, online store, content business, craft company, recruiting service, agency, IT company, or another professional service. Some businesses operate entirely from home, while others use a home address as an administrative base and complete the actual work elsewhere.
For example, a photographer may handle editing, accounting, and client bookings from home while completing photo sessions at customer locations. A cleaning business owner may manage scheduling, marketing, and administration from a home office while employees or contractors provide services at customer properties.
Depending on the size of the operation, a home-based e-commerce seller may store inventory and fulfill orders from a spare room, garage, storage facility, or third-party logistics provider. The right setup depends on the business model, product type, customer demand, and available resources.
Confirm If the Business Truly Suits a Home Setting
Running a home-based business still requires careful planning. Several practical factors can affect whether your business is suitable for a home environment. These include customers visiting your property, inventory storage, equipment needs, employees, food preparation, noise, deliveries, signage, and other operational requirements.
A home-based business is not automatically free from regulations. You may still need to consider zoning rules, business licenses, local permits, insurance requirements, homeowner association rules, lease restrictions, and food-safety regulations.
Before investing in equipment or advertising, confirm that your planned business activity is allowed in your location. You should also check whether your industry requires specific licenses, insurance coverage, health approvals, or safety requirements. A business that appears simple to start online may involve significant regulatory challenges when operated from home.
Home businesses are often more practical when the work is knowledge-based, digitally delivered, appointment-based, or requires limited inventory and customer traffic. If flexibility and lower overhead are important goals, the Home Business Ideas section can help identify opportunities that can be operated from home or managed primarily through a home office.
Low-Cost Business Ideas
Low-capital ventures appeal because most are revenue-positive, letting you test demand with relatively little capital at risk. Yet the crucial difference is between low cost and no cost. Every real enterprise eventually incurs costs, even if the founder already owns the key equipment.
A solo consultant might need software, domain name registration, professional insurance coverage, accounting assistance, marketing services, payment processing solutions, and boardroom tools or licensing. In this case, a local service provider needs transportation, equipment, protective gear, insurance, and advertising. While a freelancer may have a computer, they will still need software subscriptions, business registration, portfolio tools, and customer-acquisition resources.
So the goal isn’t to literally spend zero. This is to avoid incurring fixed costs too early, while you still need proof of concept that customers are willing to pay.
Services Are Often Good Candidates for Lean Launches
Some skills-based businesses start with assets that the founder already has. Professional services, on the other hand, including tutoring, consulting, freelance writing, pet sitting, virtual assistance and social-media management, bookkeeping and mobile services, design and some local maintenance businesses can typically be validated at lower cost than inventory-heavy businesses. The early revenue can next be ploughed back into better systems, equipment, branding, marketing and more capacity
It mitigates the risk of building a costly operation without knowing whether there is demand, hence the sell-before-scaling approach. For example, a consultant may work from home instead of immediately renting office space. For example, a service company could start with just one vehicle instead of purchasing several. Instead of immediately ordering huge volumes of inventory, a product business might start with a smaller, more manageable inventory.
You need to have more realistic estimates for startup costs. Startup expenses come into play before launch, and the U.S. Small Business Administration suggests these calculations help entrepreneurs estimate profits, identify what is needed to break even, and understand cash needs and how much funding is required. Just because a business is prepaid for $500 does not mean it is better than one billed $20,000. The better investment is the one where the demand (i.e., what you want to invest in and why), as well as the founder’s risk tolerance and financial status, make sense before an investment offer comes through your mailbox.
Based on that, low-cost business ideas should be ones you can test/operationalize without the capital burdens commonly expected in many storefronts, manufacturing, or inventory-based companies.
Service Business Ideas
Unlike physical goods, service businesses trade on expertise, labor, convenience, access management, and a finished product. They exist in every sector and serve consumers, businesses, or both.
You sell cleaning, landscaping, tutoring, photography, pet care, repairs, moving assistance, beauty services, event services, personal training, and home maintenance to residential customers. Businesses also buy accounting, consulting, IT help, marketing, recruiting, and legal services, and repair add-ons for hundreds of specialized services. Because of this diversity, service businesses are a great option for entrepreneurs with skills that can help others and who don’t want to get into manufacturing or stocking products.
The Best Service Businesses Sell an Outcome
A common mistake is pricing and defining a service only around the tasks involved. Customers usually care less about the process and more about the result. A business owner may not care that a marketing consultant spends five hours analyzing campaigns. They care about whether the marketing strategy improves performance. Similarly, homeowners value having a well-maintained yard without spending their own time mowing the grass.
Focusing on outcomes can improve packaging, positioning, marketing, and pricing. Instead of saying, “We provide ten hours of bookkeeping each month,” a company could highlight the benefits: accurate financial records, better visibility, and fewer administrative headaches. A marketing agency could position its service around helping a specific type of business maintain a professional online presence rather than simply selling “three social media posts per week.”
Service companies can also improve revenue predictability by converting suitable one-time services into recurring relationships. Examples include monthly bookkeeping, regular landscaping, recurring commercial cleaning, IT management, equipment maintenance, pest control, and ongoing consulting. Recurring revenue does not automatically mean higher profits, but it can reduce the pressure of constantly finding new customers and make financial planning easier.
Productizing a Service
The more standardized their work, the easier it is for some service businesses to sell and operate. Where a company might otherwise offer unlimited “marketing consulting,” it may instead offer an explicit market-positioning audit with a clear scope, timeline, deliverables, and price. Web designers may develop a template website offering for people in the same industry instead of pricing out each project individually.
Standardization is an essential ingredient in customer comprehension of what they actually are purchasing, as well as delivery ease where it can be trained, delegated, measured, and improved. It can also help mitigate scope creep and provide more standardized pricing. Service Business Ideas: For entrepreneurs looking for Value business ideas, monetizing expertise, labor, convenience, or professional capability.
Profitable Business Ideas
It is understandable to ask for a profitable business idea, but people often miss what profitability actually means. No business category guarantees profit. Two people can start businesses in the same field selling similar items yet end up with entirely different financial results because of pricing, operating costs, customer retention, location, marketing effectiveness, debt acquisition, productivity, competition, and management skills.
A more productive approach is to look at the characteristics that underlie the attractive economics of business opportunities. Instead of limiting the question to how much revenue a business can generate, look at what is left after paying for all the costs that go into generating that revenue.
Look for Healthy Unit Economics
After direct costs incurred to deliver that sale, calculate the revenue left over for each sale. An expensive service business that has a small cost of goods but potentially great gross margins is limited in growth by labour capacity. A retailer may record significant revenue alongside high product expense. Once the product is built, software typically has low incremental delivery costs, but building, supporting, and infrastructure the software can be expensive, along with customer acquisition.
Every model has tradeoffs, and understanding what works for you is more valuable than chasing lists of the supposed “most profitable biz.” Strong unit economics often have several sources, such as sufficient pricing power, low delivery costs, efficient customer acquisition and retention, and disciplined overhead.
Favor Problems That Customers Are Motivated To Solve
Demand is usually higher when the issue has financial, practical, emotional, regulatory, or time implications—zero margin for error. Operationally, accounting matters. Homeowners are forced to pay for major emergency repairs, as delaying urgent leak repairs will only lead to even costlier long-term damage! Security breaches matter, which is why companies invest in cybersecurity.
Not every successful business has to solve an immediate problem, though. Entertainment, fashion, hobbies, recreation, food, travel, and discretionary spending support massive markets. It does, however, mean that you understand the degree and type of motivation behind the purchase. If it’s very important to the customer, they can imagine paying a significant price quite easily.
Think about Repeat Purchases and Customer Lifetime Value
A business does not always need thousands of new customers if existing customers continue buying. A cleaning company, for example, may serve the same customer every week. A subscription software company can generate recurring revenue from ongoing payments. A bookkeeping firm may retain clients for several years, while a specialty retailer can benefit from repeat purchases from loyal customers.
Strong customer retention can significantly improve a business’s economics. Acquiring a new customer usually requires more time and money than generating another sale from an existing satisfied customer. Businesses with strong repeat-purchase patterns may be able to spend more on customer acquisition while still remaining profitable over time.
In the Profitable Business Ideas section, readers can explore businesses where revenue models, cost structures, market demand, and repeat-purchase potential create attractive opportunities. However, profitability ultimately depends on execution, effective management, and the ability to deliver consistent value to customers.
Industry-Specific Business Ideas
The simplest way to discover a strong business opportunity is often not to start with a business model. Start with an industry you can relate to. Every industry has inefficiencies in its business model, underserved customer groups, specialized workflows, compliance complexity, a changing technology landscape, and local optimizations or burning issues. Because outsiders lack industry knowledge, those opportunities might not even register.
A construction worker may be familiar with challenges in subcontractor management, equipment, inspections, estimating, job-site cleanup, or specialized services. But if you have hospitality experience, catering, staffing, food supply, reservations, events, or guest services teams might tell you where they need coverage. For example, someone with healthcare administration experience might recognize operational hurdles that a generalist entrepreneur would not easily spot.
Food and Hospitality Businesses
Food businesses include restaurants, catering services, meal preparation companies, bakeries, specialty food brands, and mobile food operations. They also include businesses that serve the hospitality and event industries. Demand can be strong in this sector, but operators must understand several important factors. These include food costs, staffing, waste management, capacity planning, permits, health requirements, delivery logistics, and customer demand.
A food truck, for example, is much more than a restaurant on wheels. Location strategy, event opportunities, licensing, menu planning, equipment reliability, and food preparation processes all affect performance. Even small operational details can influence service speed and customer satisfaction.
Food businesses are often highly operational and regulated. They require careful planning beyond the simple descriptions people usually see online. Businesslineer already covers individual opportunities like food trucks in greater detail. These topics are better suited to dedicated supporting guides rather than being fully explained within a single pillar page.
Home, Property, and Construction Services
It becomes a massive eco system of businesses based on the source of your property. Cleaning, landscaping, painting, pressure washing, pest control, inspections & maintenance, remodeling & repair work, including plumbing and electrical services for professionals completing their contracts; property management or moving/ junk hauling machines- basically everything that is responsive to repeated demands of houses + commercial structures.
Many of these businesses are easy to defend locally because they require physical work close to the customer. For example, a plumber in one city does NOT directly compete with a plumber hundreds of miles away. Hence, local reputation, response speed, reviews, reliability, and relationships can become true competitive advantages.
But licensing and qualifications vary widely by activity and jurisdiction. These activities include construction, plumbing, electrical work, restaurants and food businesses, transportation services, or vending; you may need local or state permits, licenses, inspections, and insurance. Entrepreneurs should investigate applicable requirements before investing heavily.
Professional and B2B Services
B2B services go far beyond marketing and accounting. Businesses often need specialized support in areas such as compliance, procurement, training, software implementation, data management, employee benefits, recruiting, logistics, process improvement, cybersecurity, documentation, sales operations, customer research, commercial maintenance, and industry-specific consulting.
B2B businesses can become especially attractive when their services create measurable financial value. For example, a company may be willing to pay $5,000 for a service if there is strong evidence that it can save $25,000, reduce risk, improve productivity, or increase revenue. The clearer the financial impact, the easier it becomes to justify the investment.
Understanding the purchasing process is also critical. The person using a service may not always be the person who approves the budget. Successful B2B companies need to communicate both operational value and financial value. They must show how their solution improves daily operations while also supporting broader business goals.
Technology Businesses
Technology opportunities cover a wide range of areas. These include Software as a Service (SaaS) products, IT support, automation solutions, cybersecurity tools, application development, data services, technical consulting, and specialized software for specific industries. However, creating a successful technology business does not always require groundbreaking innovation.
A focused technology solution can often be more valuable than an impressive product without clear demand. For example, software that solves a specific and expensive workflow problem for a particular profession may be easier to monetize. A smaller product designed for a narrow industry can also build stronger customer loyalty than a broad tool competing against established platforms.
Technology entrepreneurship also requires realistic expectations. Founders with technical skills may develop early solutions at a lower cost because they can build much of the product themselves. Others may need to outsource development, which can significantly increase expenses.
After launch, the work continues. Entrepreneurs must manage customer support, infrastructure, security, compliance, maintenance, and customer acquisition. A finished product is only one part of a successful technology business.
Education and Knowledge Businesses
Individuals and enterprises pay for skills, qualifications, data, and higher abilities. Things like tutoring, professional training, corporate workshops, test prep for all sorts of things, language learning, career coaching, educational products/resources (books/audio/video as well as text books?), niche courses in general and candidates or even instructional software/products/games can all be businesses that are plausibly run by someone who knows there stuff (or well maybe not everything) and whose customers care about the result.
This credibility is crucial when running knowledge businesses. The more serious the claim that you make about professional, financial, health, academic, or career outcomes, the stronger your evidence and expertise should be. Tell your customers why you are qualified to teach, consult, or coach them.
A key benefit of education businesses is choosing a specific audience. A business course is vague, whereas financial-management training for new restaurant owners is much easier to position. This specialization allows for more precision in the curriculum and customer-acquisition strategy.
Logistics, Rental, and Asset-Based Businesses
Certain businesses profit simply by providing access to physical goods when consumers need them. Repeat revenue from the same asset can come from rentals, trailers, event supplies and storage, specialized vehicles, tools, vending routes, or other assets.
However, utilization is critical. Storage, insurance, financing, or maintenance costs can eat into profits when equipment isn’t generating revenue, and depreciation can quickly turn profit into loss. Thus, entrepreneurs need to calculate how often a particular asset must be rented/used to recover ownership costs and produce reasonable returns.
Typically, capital planning is more intensive for asset-based businesses than for low-cost ones. Once readers have decided an asset-based model is the path for them, Businesslineer’s existing coverage of trailer rentals and vending-machine businesses can provide examples to help them pinpoint which options to explore.
Creative and Personal Services
Creative businesses include photography, design, videography, beauty services, event production, personal styling, music services, content creation, and many other creative fields. These businesses combine technical skills with creativity, customer experience, and personal style. In many of these industries, portfolio quality and reputation are important because customers often evaluate previous work before making a purchase decision.
The strongest creative businesses usually do not compete only on price. Instead, they differentiate themselves through specialization, reliability, communication, and a consistent customer experience. For example, a commercial product photographer may have a completely different brand, sales process, workflow, and pricing strategy compared with a wedding photographer.
The Industry-Specific Business Ideas section should help readers explore individual opportunities in greater depth. Each guide can examine important factors such as business economics, customer expectations, regulations, barriers to entry, and competitive dynamics within a specific industry.
How to Validate a Business Idea Before Investing Heavily
Validation is the process of replacing assumptions with evidence. You do not need absolute certainty before launching because no amount of research can eliminate entrepreneurship’s uncertainty. The objective is to test the most important assumptions cheaply enough that you can change direction before making expensive commitments.
A business idea usually contains several assumptions. You may assume that a particular customer has a problem, that the problem is important, that your solution is attractive, that the customer will pay your intended price, that you can reach enough customers, and that the resulting economics will work. Validation means testing those assumptions instead of treating them as facts.
Define the Customer Precisely
“Small businesses” is usually too broad to be a useful target market. A company serving independent restaurants has a different customer from one serving industrial manufacturers, even though both may technically be small businesses. A service for solo real estate agents may require completely different positioning from a service sold to accounting firms.
Write down who experiences the problem, what creates the problem, how frequently it occurs, what the customer currently does about it, and who makes the purchasing decision. The clearer the customer, the easier the next stages become.
Study Existing Alternatives
Search for companies already solving the problem and examine their positioning, prices where available, customer reviews, service areas, product features, complaints, guarantees, delivery methods, and target audiences. Competitive research should not be conducted merely to copy competitors. Its purpose is to understand how the market currently works and where gaps may exist.
Customers may repeatedly complain about slow response times. Existing products may be designed for large enterprises while smaller customers remain underserved. Service providers may ignore a particular geographic area. Companies may offer complicated solutions where customers prefer simplicity. These gaps can become positioning opportunities if enough customers care.
The U.S. Small Business Administration recommends combining market research with competitive analysis to identify customers and develop competitive advantages. The goal isn’t to prove your idea is unique. The goal is to determine whether it has a credible place in the market.
Talk to Potential Customers
Customer conversations can reveal information that keyword tools, social media, and industry reports cannot. Ask how people currently handle the problem, what frustrates them, what they have already tried, what the problem costs them, and what would cause them to switch solutions.
Avoid leading questions such as, “Would you buy my amazing new service?” People frequently respond positively to hypothetical ideas because saying yes costs nothing. Questions about actual behavior are stronger. Ask when they last paid someone to solve the problem, what they chose, how much it cost, what they disliked, and what would make them change providers.
Past behavior is often more informative than hypothetical enthusiasm. A person who has already spent money to solve a problem is generally a stronger signal than someone saying they might buy something someday.
Test the Smallest Credible Offer
Whenever possible, seek market evidence before building the full business. A consultant can sell a pilot engagement, a service provider can start within one neighborhood, an educator can conduct a live workshop before creating a large course library, and an e-commerce founder can test a narrow product range before ordering a massive catalog.
A software founder may use a prototype, manual process, or limited version to determine whether the problem is important enough for customers to pay to solve it. The objective is not to launch something poor. It is to avoid investing months or large amounts of capital in features customers never asked for.
Your first version only needs to be credible enough to test the core value proposition. Once customers use or buy it, their behavior can show what deserves further investment.
Calculate Basic Economics
Estimate your realistic selling price, direct cost per sale, monthly fixed expenses, required startup investment, expected sales volume, and customer-acquisition costs. Then determine roughly how many sales are required to cover the business’s costs.
Break-even analysis can be useful because it shows how many units, projects, subscriptions, or customer relationships must be sold before revenue covers expenses. Forecasts will be imperfect, especially before launch, and that is acceptable. Early financial modeling isn’t meant to predict the future precisely. It is to expose assumptions.
If the business only works when you assume unrealistically high prices, nearly zero marketing costs, perfect utilization, and immediate demand, the model needs more work. A simple spreadsheet based on conservative assumptions can reveal problems before they become expensive.
From Business Idea to Business Launch
Once a concept has survived initial validation, the next step is turning it into an operating business. Start by clearly defining the offer: the customer, problem, solution, pricing model, and delivery process. Then estimate startup and operating expenses and decide what must exist before the first customer and what can wait until revenue begins.
Your legal structure also deserves careful consideration. Common U.S. structures include sole proprietorships, partnerships, corporations, and limited liability companies, but their legal, administrative, and tax consequences differ. The business form you choose can affect taxation, liability, ownership, fundraising, and compliance, so the decision should reflect your actual circumstances rather than a generic recommendation found online.
Don’t choose a legal structure just because an influencer says every entrepreneur needs one particular entity type. Your location, ownership structure, liability exposure, tax situation, industry, and plans matter. When the consequences are significant, consult an appropriately qualified legal, accounting, or tax professional.
You should also determine registration, licensing, insurance, tax, zoning, and permitting requirements. These differ by jurisdiction and business activity. Food, construction, transportation, professional services, childcare, healthcare, financial services, and other regulated industries can require additional approvals or qualifications.
After you address the administrative foundations, focus relentlessly on getting real customers. A logo is not validation, a domain name is not validation, business cards are not validation, and a complicated software system is not validation. A paying customer is evidence that someone values the solution enough to exchange money for it.
Early customers also create the feedback needed to improve the offer. Listen carefully to why they bought, what almost prevented the purchase, which parts of the experience they valued most, and what problems remain. Then refine the product, service, pricing, sales process, and delivery model around what you learn.
Common Mistakes When Choosing a Business Idea
One of the most common mistakes is choosing an idea because it is fashionable rather than because the founder has identified a durable customer need. Trends can create legitimate opportunities, but they also attract competition and exaggerated income claims. A business becomes stronger when its demand rests on something more substantial than temporary online attention.
Another mistake is confusing revenue potential with profitability. A company can sell a large amount and still produce little owner income after product costs, payroll, advertising, rent, transportation, software, taxes, debt payments, and other expenses. Entrepreneurs should therefore examine margins and cash flow rather than judging an opportunity only by top-line revenue.
Founders also frequently underestimate customer acquisition. Building a product or learning a skill is only one side of the business. You need a repeatable way for the right customers to discover, trust, and buy from you. If a business requires expensive advertising to acquire each customer and those customers rarely return, the economics can become difficult even when the underlying product is good.
Overinvesting before validation creates another unnecessary risk. Expensive branding, inventory, equipment, leases, technology, and staff should correspond to evidence of demand rather than optimism alone. Many founders would benefit from delaying nonessential expenses until they know which parts of the business customers actually value.
Ignoring regulatory requirements can be considerably more serious. Food, construction, healthcare, financial services, childcare, transportation, professional services, and other regulated fields may have licensing, safety, insurance, or qualification requirements that affect whether and how you can operate. Research these issues before accepting customers or spending heavily.
Finally, be skeptical of business opportunities marketed around guaranteed earnings, effortless passive income, secret systems, or unusually large returns. The Federal Trade Commission has repeatedly warned consumers about business opportunities and coaching programs that use guaranteed-income or large-return claims. Legitimate businesses still require customers, economics, execution, and risk.
How to Build a Business That Can Grow
A successful first sale is important, but a repeatable business is more valuable. Once you’ve established demand, examine which parts of the operation depend entirely on you. Document repetitive work, create standard processes, improve quoting and onboarding, track customer acquisition, measure margins, and identify frequent customer questions.
Build systems for scheduling, invoicing, fulfillment, follow-up, quality control, and customer retention. You do not need to automate everything. The goal is to prevent the company from relying on improvisation every time a customer arrives.
Growth can take several forms. You may serve more customers in your existing market or increase your prices by creating a stronger offer. Other options include adding complementary services, expanding into new locations, developing recurring revenue streams, hiring employees, working with contractors, selling additional products, or entering new customer segments.
The best growth strategy depends on your business model, economics, and long-term goals. A solo consulting company may choose to remain small while generating strong profits. In contrast, a cleaning company may expand by building teams across multiple locations. An e-commerce company may grow by adding new product categories, while a software company may focus on increasing its subscriber base. Growth should support the owner’s goals instead of becoming a goal by itself.
Which Type of Business Idea Should You Explore?
Your starting point should reflect your strongest constraint, preferred business model, and long-term goals. Entrepreneurs looking for a traditional or locally focused opportunity can explore Small Business Ideas. Those who prefer geographic flexibility, digital distribution, or internet-based customer acquisition may find Online Business Ideas more suitable. For people who want to operate from home, Home Business Ideas provides opportunities designed around flexibility and lower overhead, while those with limited startup capital should consider Low-Cost Business Ideas.
Entrepreneurs who want to monetize expertise, labor, convenience, or professional skills can explore Service Business Ideas. Those focused on business models with strong revenue potential and attractive economics can review Profitable Business Ideas, while keeping in mind that profitability depends on execution, market demand, and management. Readers who already have a specific industry in mind can explore Industry-Specific Business Ideas to discover opportunities within that field.
These categories overlap, and that is intentional. A bookkeeping company can simultaneously be a small business, online business, home business, low-cost business, service business, potentially profitable business, and industry-specific professional service. Categories help you discover opportunities; they do not need to define the company permanently.
Frequently Asked Questions About Business Ideas
What Is the Best Business to Start?
There is no universally best business. The strongest choice depends on demand, competition, startup costs, skills, access to customers, location, risk tolerance, and personal objectives. A business that is ideal for an experienced software engineer may be completely inappropriate for someone who wants a hands-on local company. Instead of searching for one “best” idea, identify several opportunities that match your circumstances and validate them.
What Is the Easiest Business to Start?
Skills-based service businesses are often relatively simple to test because they may require little inventory or specialized infrastructure. Examples include freelancing, consulting, tutoring, virtual assistance, certain home services, and creative services. However, “easy to start” does not mean easy to succeed in. Customer acquisition, pricing, differentiation, reliability, and delivery still matter.
What Business Can I Start With Little Money?
Many service and online businesses can be launched with relatively low upfront costs, particularly when you already possess the necessary skills and equipment. Examples can include consulting, writing, design, tutoring, pet services, virtual assistance, certain cleaning services, and specialized freelance work. Calculate your actual startup costs before committing because insurance, licensing, software, marketing, equipment, transportation, and other expenses vary significantly.
What Businesses Can I Run From Home?
Consulting, bookkeeping, tutoring, design, marketing, virtual assistance, software development, digital products, online education, certain e-commerce businesses, and numerous freelance services can operate from home. Some physical businesses can also use a home as their administrative base. Check local zoning, lease or homeowner restrictions, permits, insurance, and industry regulations before assuming a particular activity is allowed from your residence.
How Do I Know Whether People Will Buy My Business Idea?
Look for behavioral evidence. Study competitors, speak with target customers, examine what people currently pay for, identify dissatisfaction with existing solutions, and test a small paid offer. A customer saying an idea sounds interesting is weaker evidence than someone paying for a pilot product or service.
Should I Start a Business in a Market With a Lot of Competition?
Competition is not automatically bad. It often proves that customer demand exists. The question is whether you can give a specific group of customers a meaningful reason to choose you. That advantage could come from specialization, location, convenience, service quality, speed, expertise, customer experience, pricing, technology, or a different business model.
How Much Money Do I Need to Start a Business?
There is no universal startup figure. A freelance service may need relatively little capital, while a restaurant, manufacturing operation, franchise, transportation company, or equipment-heavy business may require substantial funding. Estimate one-time startup expenses, recurring monthly costs, working capital, and personal financial needs before launching.
Do I Need an LLC Before Testing a Business Idea?
Not every business automatically requires the same legal structure. Business structure affects taxation, administration, fundraising, ownership, and liability, and requirements differ by location and situation. Research the applicable rules and obtain qualified professional advice when legal or tax consequences are material.
Are Online Businesses Still Worth Starting?
Online businesses can still offer significant opportunities because they can reach customers beyond a local market and support many different models, including services, products, software, education, and digital media. The challenge is that accessibility also attracts competition. Success depends on solving a meaningful problem, developing a compelling offer, reaching customers economically, and avoiding excessive dependence on a single platform.
How Long Should I Test a Business Idea Before Launching?
There is no fixed testing period. The appropriate amount of validation depends on cost and risk. A low-cost freelance service can often be tested quickly because little capital is at stake. In contrast, a restaurant, regulated service, manufacturing operation, or asset-heavy company requires more research because mistakes cost more. The goal is to gather enough evidence to justify the next level of investment, not to eliminate every uncertainty.
Turn the Idea Into Evidence
The purpose of exploring business ideas is not to keep collecting ideas forever. Eventually, you need to choose something worth testing. Begin with your skills, resources, goals, and constraints, then identify a real customer, understand the problem, study how customers solve it today, analyze competitors, estimate your economics, and check legal and operational requirements.
From there, create the smallest credible version of your offer and put it in front of the market. You may discover that the original idea needs to change, but that is not wasted effort. Discovering weak assumptions before investing heavily is one of validation’s most valuable outcomes.
The strongest entrepreneurs are not necessarily the people who identify a perfect concept immediately. They learn systematically, respond to real evidence, understand their customers, manage risk intelligently, and keep improving the business after launch.
Use the Businesslineer Business Ideas hub as your starting point, then go deeper into the category that best matches your situation: Small Business Ideas, Online Business Ideas, Home Business Ideas, Low-Cost Business Ideas, Service Business Ideas, Profitable Business Ideas, or Industry-Specific Business Ideas.
A business begins with an idea, but a sustainable business begins when that idea survives contact with real customers.